How Can I Reduce My Card Processing Fees?
By That Card Machine Guy
To find out how to reduce card processing fees, work out your effective rate first. Add up the card-related charges for a period, divide them by your card takings for the same period, then multiply by 100. That gives you a clearer starting point than a headline rate alone.
Once you know what you pay, check which parts of the bill could change: your percentage rates, transaction charges, terminal rental and recurring fees. You may be able to negotiate or switch, but the cheapest headline rate is not automatically the cheapest bill.
What could reducing your fees look like?
Imagine a small business takes £10,000 per month across 400 card transactions, an average of £25 per payment. Its current monthly charges are:
| Charge | Current estimate |
|---|---|
| Percentage fee: 1.3% of £10,000 | £130 |
| Transaction fee: 400 × 10p | £40 |
| Terminal rental | £18 |
| Total per month | £188 |
Its effective rate is £188 ÷ £10,000 × 100 = 1.88%.
Suppose the business reviews its costs and gets a different estimate: a 1.2% percentage fee, 5p per transaction and £10 monthly rental.
| Charge | New estimate |
|---|---|
| Percentage fee: 1.2% of £10,000 | £120 |
| Transaction fee: 400 × 5p | £20 |
| Terminal rental | £10 |
| Total per month | £150 |
That is an estimated saving of £38 a month, or £456 a year if turnover and fees stayed the same. The new effective rate would be £150 ÷ £10,000 × 100 = 1.5%.
This is a simplified example, not a quote. It assumes the same card sales and transaction count under both options, and no other fees. Actual costs depend on your card mix, contract and any additional charges.
Which costs should I check first?
What is your full merchant service charge?
Start with your merchant statement and pricing schedule. A merchant service charge (MSC) may be shown as one combined figure or broken into different charges. Ask for a clear breakdown of the percentage rates, scheme or processing charges, the provider’s charges, and any fixed fees.
Some underlying costs may not be negotiable. For example, UK interchange caps apply to certain domestic consumer transactions, but they do not cap the full MSC. The Payment Systems Regulator explains the distinction in its guide to the IFR and merchants. The provider’s own pricing and other parts of your bill may still be worth reviewing.
Are your card types priced fairly?
Debit, credit and commercial cards may have different rates. So can payments taken in person and online. Ask what card mix a quote assumes, and compare it with the mix you actually take.
When entering a card mix into a calculator, use each type’s share of sales by value if that is what your pricing is based on. Don’t count one payment in two categories. A quote based mainly on debit cards might not reflect your costs if a larger share of your sales comes from credit or commercial cards.
Do per-transaction charges suit your average sale?
A fixed charge applies to each payment, so it can matter more if you take lots of small payments. For example, 10p is 1% of a £10 sale, but 0.2% of a £50 sale.
Check the price per transaction as well as the percentage fee. Use your actual transaction count when comparing business card processing rates. Two businesses with the same turnover could pay different amounts if one processes many more payments.
Is terminal rental worth the cost?
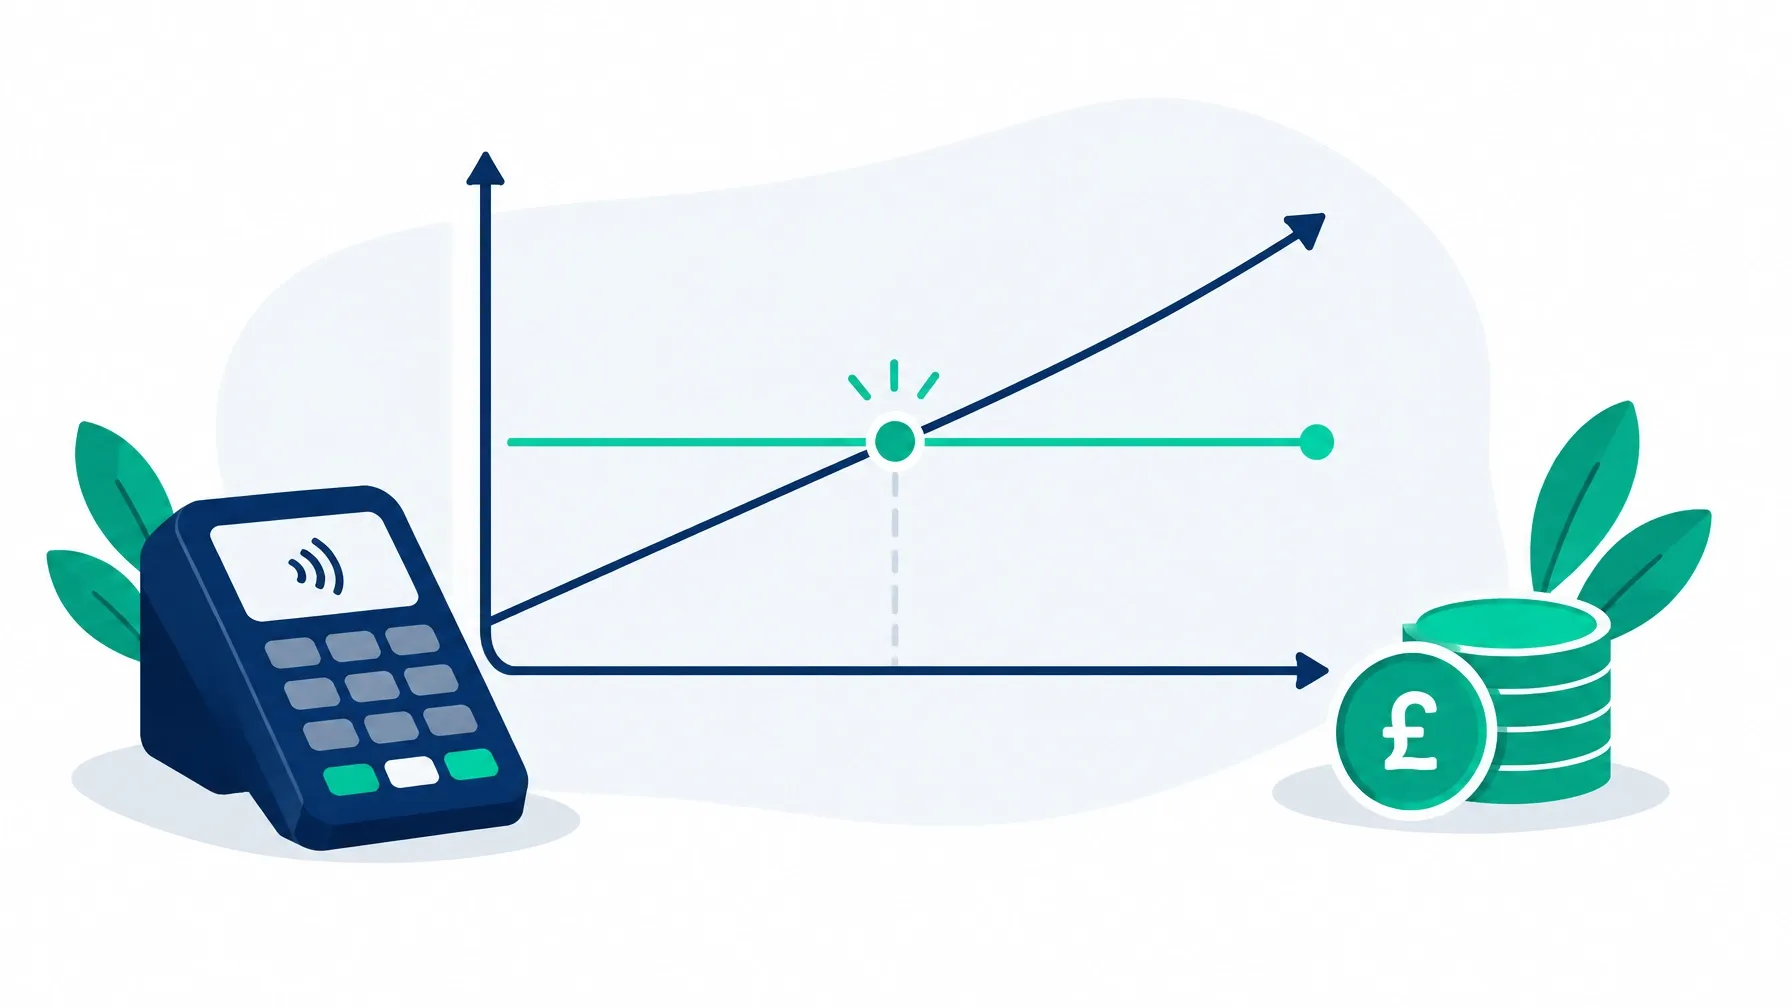
Compare your current rental with alternatives, such as buying a terminal or using a reader with no monthly rental. Look at the total cost, including the device price, transaction rates, support, connectivity and contract terms. A no-rental option may have a higher percentage fee, while a rented machine adds a fixed charge even in a quiet month.
Are recurring fees necessary and clear?
Check for PCI, statement, account, gateway, software, connectivity and minimum monthly charges. Find out what each fee covers and whether it is charged monthly or annually. A minimum charge can matter particularly in a quieter or seasonal month, when transaction fees may be low.
Don’t remove a security service or assume a PCI fee can be avoided without checking your obligations and contract. Instead, ask what the charge covers, what you need to do to remain compliant, and whether you are paying for a service you do not use.
Is it time to renegotiate or compare providers?
If your turnover has grown, your transaction pattern has changed or your current costs have become hard to explain, ask for an updated price. You can also get competing estimates using the same card turnover, transaction count and card mix. That makes a merchant services comparison in the UK more useful than comparing advertised percentages.
Before assuming you are locked in, check your contract’s term, notice period, renewal conditions and any fees for ending or changing services. A new quote is not necessarily a saving if it comes with higher fixed charges or an unsuitable contract.
What mistakes can make a comparison misleading?
- Comparing headline percentages only: fixed transaction and monthly fees can change the total.
- Forgetting your transaction count: this can hide the cost of per-payment charges.
- Comparing different periods: match your card takings and fees to the same dates.
- Using the wrong sales figure: use card takings, not total business revenue including cash or bank transfers.
- Adding a fee twice: if you start with the total bill, some itemised charges may already be included.
- Treating an estimate as a quote: refunds, chargebacks, international cards, minimums, VAT treatment and billing dates can affect the actual bill.
A lower price may not be possible for every part of your bill, and switching is not always the right answer. Focus on the complete cost and the terms that apply to your business.
How can I calculate and compare my own costs?
Use the free Card Fee Check calculator. In the From my bill tab, enter your card turnover and total fees to see your estimated effective rate. For a more detailed estimate, add your card mix, transaction charges, terminal rental, PCI fees and other monthly costs. You can also use Compare another provider to compare estimated monthly and annual costs using the same sales figures.
This is an effective card rate calculator, not a provider recommendation. You do not need to upload a statement, and calculations take place in your browser. Results are estimates based on the figures you enter. Read how the estimates work before using them to compare an actual quote.
Which guides can help me check the details?
- How to Calculate Your Effective Card Processing Rate, work out what you pay now.
- Card Machine Rental vs Transaction Fees, see whether a fixed rental or a higher transaction rate suits your turnover.
- Why a Low Headline Rate Can Still Mean a High Bill, understand why a lower advertised percentage can cost you more.
- What Does a 1% Card Fee Cost Per Month?, turn a percentage into pounds and pence at your turnover.
- How to Read a Merchant Statement, find every charge on the bill you are trying to reduce.
- Back to all Card Fee Guides
The person behind the calculator
About the author
Written by That Card Machine Guy. I run CardFeeCheck and also help UK businesses with card machines and processing costs. The calculator is free, independent and provider-neutral.